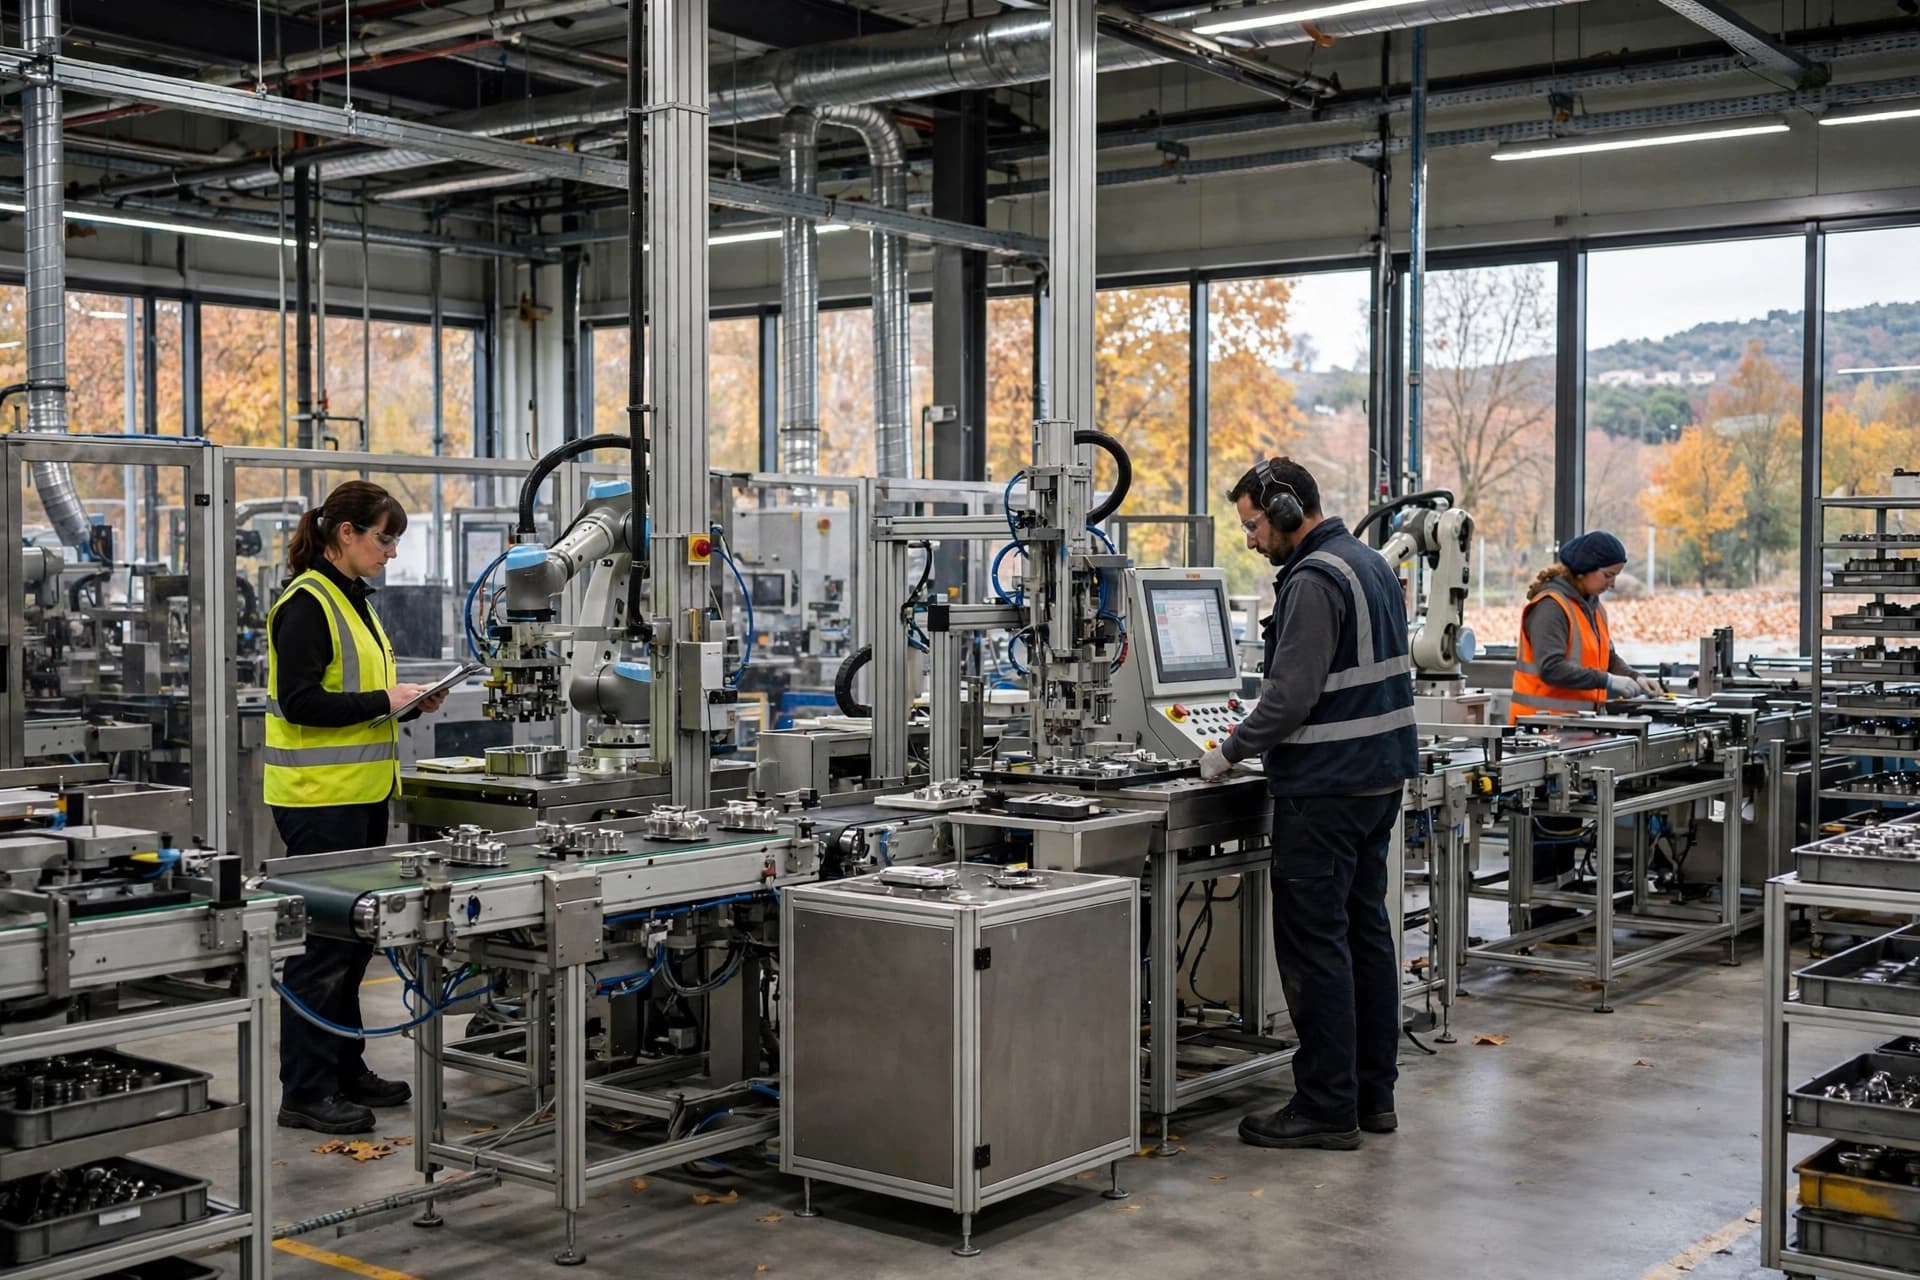
Spain’s manufacturing activity returned to growth in September after several months of contraction. The S&P Global Manufacturing Purchasing Managers’ Index rose to 51.0 from 49.5 in August, moving above the 50-point threshold that separates expansion from contraction.
The improvement came as production increased after three consecutive monthly declines. Export orders also rose for the first time since August 2025, giving factories another source of activity at a time when domestic demand remained comparatively subdued.
Yet the headline improvement does not describe an economy without pressure. Overall new orders fell for a fifth consecutive month, according to the survey, with companies pointing to uncertainty and higher prices as factors affecting demand.
Energy costs were an important part of that picture. Input-cost inflation accelerated to its highest level in four months, while manufacturers increased their selling prices at the fastest pace in three months as some of those higher costs moved through to customers.
The combination creates a familiar tension for manufacturers. Stronger production can provide breathing room, but higher costs can make every additional unit more expensive to produce. Companies therefore have to navigate two different currents at the same time: finding new demand while protecting margins.
Employment offered another sign of stabilization. The survey showed employment was unchanged in September, ending a twelve-month period of net job losses. Some companies began hiring in response to firmer workloads, although the overall employment picture remained cautious.
Business confidence also improved. Expectations for demand over the coming year rose to their highest level since February, suggesting that manufacturers saw reasons to anticipate stronger activity even as current orders remained under pressure.
For Spain’s industrial companies, export markets may therefore become increasingly important. The first increase in new export orders since August 2025 provides a potentially useful counterweight to the continued weakness in total new orders.
Still, September’s PMI should be read as a monthly signal rather than a complete transformation of the manufacturing economy. One month above 50 does not erase the contraction seen earlier in the year, and the persistence of higher energy and input costs remains a factor businesses must manage.
The September figures nevertheless offer a different rhythm after several difficult months. Spanish factories produced more, export orders returned to growth and confidence strengthened, even while total demand remained fragile. As autumn begins, the manufacturing sector has regained some forward motion, leaving the coming months to show whether that movement can become more durable.
Published by Banx Network. This article is part of the Banx decentralized media programme, powered by the BXE token on the XRP Ledger.