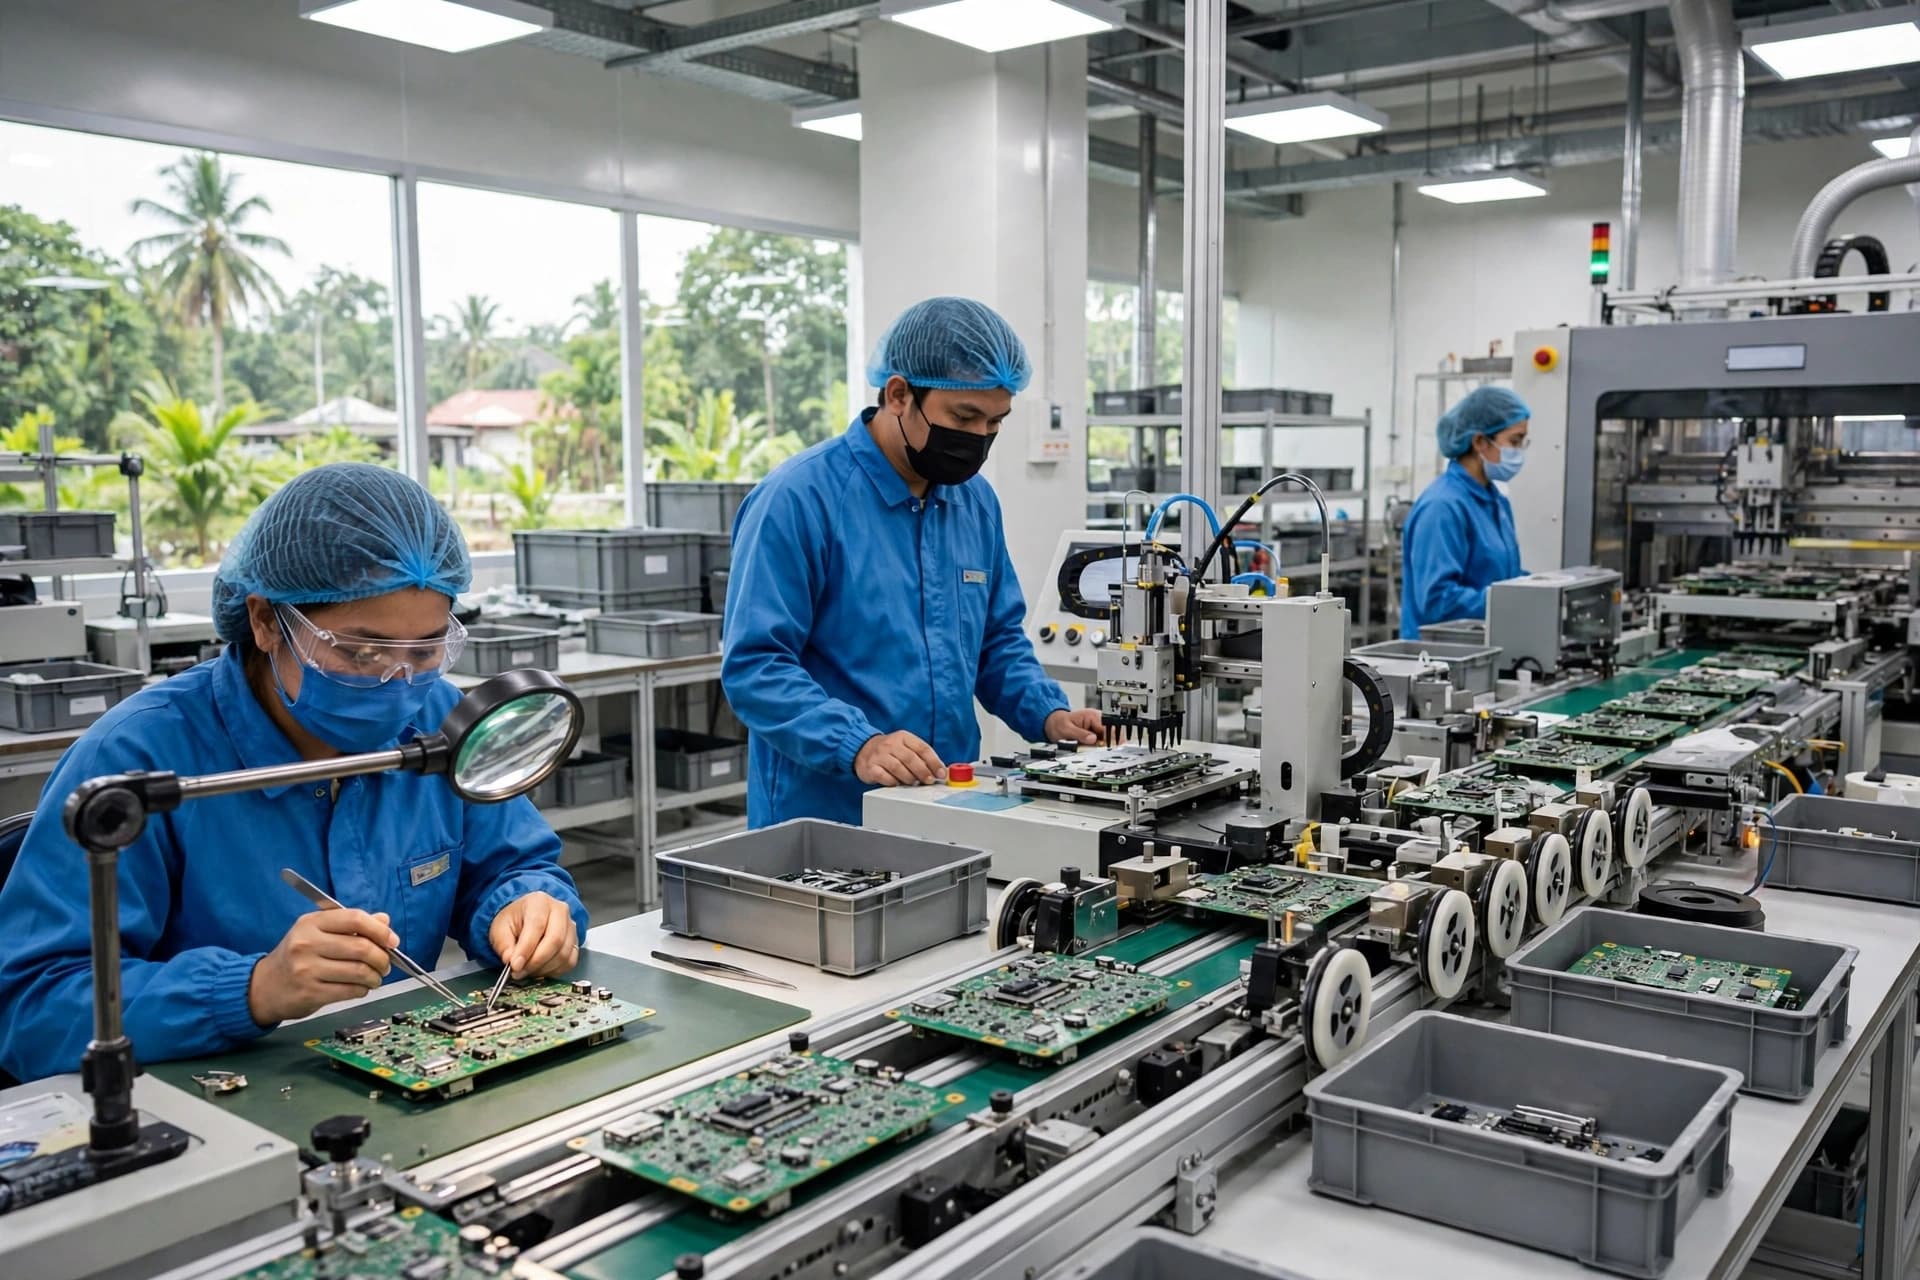
The movement of the global economy can sometimes be seen in the smallest industrial details: a new order arriving at a factory, a shipment of electronic components leaving a warehouse, or another production line preparing for a longer shift. These changes may seem local, but together they reveal how investment in one part of the world can influence factories thousands of miles away.
September brought encouraging signs for manufacturing across parts of Europe and Asia. Reuters reported on October 1 that business surveys showed stronger factory activity in several economies, with demand connected to artificial intelligence investment providing an important source of support. The expansion was not universal, but the overall picture suggested that parts of the industrial sector were gaining momentum.
In Europe, the eurozone’s manufacturing Purchasing Managers’ Index rose to 52.9, its highest reading since May 2022. A reading above 50 indicates expansion. Demand for capital goods, including equipment used in industrial and technology infrastructure, helped support the improvement, with the Netherlands and Germany among the countries benefiting from stronger orders.
Asia’s performance was also shaped by the global technology cycle. South Korea recorded its fastest export growth in more than 15 years, while Taiwan’s manufacturing PMI rose to 56.7. Both developments reflected the importance of semiconductor production and related technology demand in the region’s industrial landscape. These industries supply components that support computing, telecommunications, and increasingly sophisticated digital services.
Indonesia and Vietnam also recorded manufacturing expansion, according to the Reuters report. Their participation matters because regional supply chains extend beyond the largest chipmakers. Component production, assembly, packaging, transport, and other supporting services can allow economies to benefit from increased demand even when they do not manufacture the most advanced semiconductors themselves.
Artificial intelligence has become a significant source of investment in data centers, computing equipment, and specialized hardware. The effect reaches manufacturers that supply servers, electrical systems, cooling equipment, and other infrastructure. When technology companies expand their capacity, the resulting orders can support activity across a wider network of industrial suppliers.
Still, the improvement comes with limits. Higher energy costs and rising interest rates continue to affect manufacturers, while demand remains uneven between countries and sectors. Japan, for example, experienced weaker domestic production even as export orders remained comparatively strong. This contrast shows how international demand can support some factories while local conditions restrain others.
For manufacturers, stronger survey readings can improve confidence, but they are not a guarantee of lasting growth. Companies must decide whether rising orders justify new equipment, additional workers, or expanded facilities. Those decisions often depend on how durable demand appears, how much financing costs, and whether suppliers can deliver materials on time.
The wider economic significance lies in the connection between technological investment and industrial production. AI may be discussed as software and digital intelligence, yet its expansion relies on factories, energy systems, transport networks, and physical infrastructure. The digital economy still depends on a material foundation.
September’s manufacturing data offered evidence of renewed activity in several important economies, but also reminded observers that growth remains uneven. Whether the improvement continues will depend on the durability of technology spending, the cost of energy, and the willingness of businesses to keep investing beyond the current wave of demand.
SEO Slug: `global-factory-activity-ai-investment-september-2026`
Hashtags: #GlobalManufacturing #ArtificialIntelligence #Semiconductors #AsiaBusiness #EuropeanIndustry #IndonesiaBusiness #EconomicGrowth
Image Disclaimer
The illustrations are AI-generated conceptual representations of manufacturing and technology supply chains. They do not depict specific factories or companies mentioned in the report.
Published by Banx Network. This article is part of the Banx decentralized media programme, powered by the BXE token on the XRP Ledger.