1. The Financial Revolution Already Underway
For decades, the global financial system has relied on an intricate network of banks, brokers, exchanges, custodians and clearing houses to transfer money and record ownership.
When someone purchases shares, for example, the transaction may involve several organisations responsible for matching orders, verifying ownership, transferring funds and updating records. These processes are essential, but they can introduce delays, administrative costs and operational complexity.
Tokenisation offers a different approach.
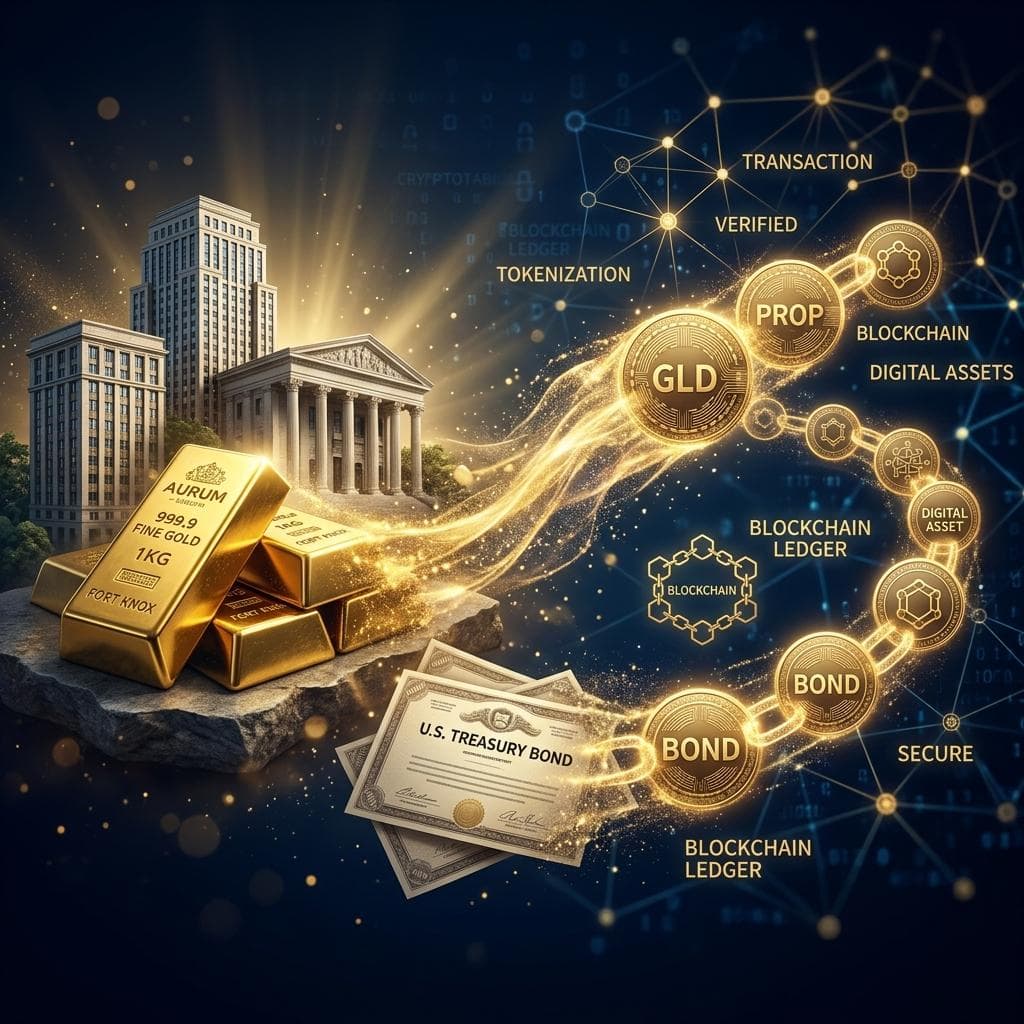
It involves creating a digital representation of an asset, or its ownership rights, on a blockchain or another form of distributed ledger technology (DLT). The asset could be a government bond, company share, investment fund, property interest or commodity.
Instead of relying exclusively on separate databases maintained by different institutions, participating organisations can use a shared digital infrastructure to record transactions and automate certain processes.
The International Monetary Fund's October 2026 analysis describes tokenisation as a technology that could bring asset issuance, trading, settlement and servicing closer together, potentially reducing the number of separate steps involved in financial transactions. However, the IMF also warns that tokenised markets remain relatively small and fragmented compared with traditional finance. [1]
The technology is therefore not replacing the financial system overnight. It is beginning to change how parts of that system could operate.
The central question is whether tokenisation can move beyond isolated experiments and become a reliable foundation for global markets.
2. What Exactly Is Tokenisation?
Tokenisation can sound complicated, but the basic concept is relatively straightforward.
Imagine a company wants to raise money by issuing bonds. Traditionally, ownership records and transfers would be managed through established financial market infrastructure.
With tokenisation, the company or an authorised intermediary could represent the relevant bond interests as digital tokens recorded on a distributed ledger.
When an investor buys or sells a token, the system can record the transaction according to the rules governing that instrument.
Smart contracts—software that automatically executes predefined instructions—can also automate certain activities, such as calculating payments, enforcing transfer restrictions or distributing eligible income.
However, there is an important distinction between the token and the underlying asset.
A token representing a share does not automatically provide the same ownership rights as a conventional share. Its legal status depends on the arrangement, the issuer, the applicable law and the rights attached to the instrument.
Some tokens represent securities issued directly on a blockchain. Others represent an interest held through a custodian. Some products provide only price exposure through a separate contractual arrangement.
The US Securities and Exchange Commission's January 2026 statement on tokenised securities explains that tokenised securities remain subject to applicable securities laws, with the relevant treatment depending on how the product is structured. [2]
Tokenisation changes how an asset can be represented, transferred and managed. It does not automatically change what the asset legally is.
3. Why Financial Institutions Are Taking It Seriously
Tokenisation is attracting attention because it could address some of the financial industry's longstanding inefficiencies.
Traditional markets often depend on multiple organisations maintaining compatible records. Transactions may pass through brokers, clearing systems, custodians and settlement institutions before everything is finalised.
A shared ledger could reduce reconciliation between separate systems and make certain transactions easier to automate.
For financial institutions, even modest efficiency improvements could matter when applied to enormous volumes of transactions.
The Bank for International Settlements (BIS) has argued that tokenisation could improve cross-border payments and securities markets. In June 2025, it proposed a tokenised financial architecture that could integrate central bank reserves, commercial bank money and government bonds on a unified ledger. [3]
The idea is not simply to put existing assets on a blockchain. It is to make different parts of the financial system work together more efficiently.
In May 2026, the UK's Financial Conduct Authority (FCA) and Bank of England set out a shared vision for tokenisation in wholesale markets, identifying opportunities to improve efficiency and resilience while seeking greater clarity around regulation, collateral and settlement infrastructure. [4]
The involvement of established institutions suggests that tokenisation is increasingly being treated as a potential development in mainstream financial infrastructure rather than solely as a cryptocurrency experiment.
Yet institutional interest does not guarantee success. The technology must demonstrate that it can deliver measurable benefits without introducing unacceptable operational, legal or financial risks.
4. Could Tokenisation Make Investing More Accessible?
One of the most attractive promises of tokenisation is the possibility of fractional ownership.
Many assets are expensive to purchase outright. Commercial property, infrastructure projects, private credit and certain investment funds may require substantial capital or have restricted access arrangements.
Tokenisation could allow eligible investments to be divided into smaller digital units, potentially lowering the amount needed to obtain an economic interest in an asset.
For example, suppose a commercial property is valued at £10 million. A properly structured investment could divide the relevant ownership interests into 100,000 units worth £100 each.
An investor would not need £10 million to participate. They could potentially purchase a smaller interest, subject to the investment's terms and eligibility requirements.
This could broaden access to certain investments and allow investors to diversify across assets that would otherwise be difficult to afford.
However, fractionalisation does not automatically make an investment available to everyone.
A tokenised property interest may still be a regulated investment with restrictions on who can buy it. Minimum investment amounts, platform fees, legal structures and liquidity conditions may also apply.
There is another important limitation: owning a fraction of an investment is not necessarily the same as owning a fraction of the physical asset directly. Investors might hold shares in a company or units in a fund that owns the property.
Tokenisation can make investment interests easier to divide and transfer, but the legal structure ultimately determines what investors actually own.
5. The Market Is Growing, but the Numbers Need Context
The tokenised asset market has expanded, although its size depends heavily on what is included in the calculation.
A useful illustration comes from CoinGecko's May 2026 research, which estimated that tokenised real-world assets exceeded $19 billion by the end of March 2026, excluding stablecoins under the report's methodology. Tokenised US Treasury products accounted for a substantial share of that market. [5]
That is meaningful growth, but it remains small relative to the global markets for government bonds, equities, property and other financial assets.
More recent analysis from the IMF's October 2026 Global Financial Stability Report highlights a market with different levels of development across asset classes. Tokenised fixed-income assets outside repurchase agreements were estimated at approximately $48 billion, including around $30.4 billion in tokenised credit. Tokenised money market funds represented approximately $17.5 billion, while tokenised equity markets remained much smaller at an estimated $2.3 billion. [1]
These figures cover particular market segments and should not be added mechanically to other estimates, because definitions and categories can overlap.
They nevertheless reveal an important pattern: tokenisation is not spreading evenly across every type of asset.
Debt instruments, cash-like investment products and certain collateral arrangements have found practical uses, while broader tokenised equity markets remain comparatively limited.
The industry is growing, but the scale of the opportunity should not be confused with the amount of adoption already achieved.
6. Tokenised Bonds: A Potential Breakthrough for Capital Markets
Bonds are among the most promising applications for tokenisation.
Governments and companies issue bonds to borrow money from investors. These instruments generate interest payments and generally have defined repayment terms.
In traditional markets, issuing, transferring and servicing bonds can involve multiple systems and intermediaries. Tokenisation could simplify parts of this process by recording ownership and automating eligible payments through a shared ledger.
Government bonds are particularly interesting because they are widely used as investment assets and financial collateral.
A tokenised bond could potentially be transferred and settled more efficiently, while programmable systems could automate certain administrative tasks associated with ownership and payment.
Tokenised debt products may also make it easier for financial institutions to use eligible assets as collateral in other transactions, subject to the relevant legal and operational arrangements.
However, tokenisation does not remove the credit risk associated with the bond itself.
If a company defaults, a digital record cannot guarantee repayment. If a government faces financial difficulties, the technology does not eliminate sovereign risk.
Investors must still consider the issuer's creditworthiness, interest-rate exposure, maturity, legal rights and the arrangements governing custody and settlement.
The technology may improve how a bond is managed. It cannot make an unreliable borrower financially sound.
7. Property, Commodities and the Ownership Revolution
Beyond bonds, tokenisation could change how investors access other real-world assets.
Property: Digital tokens could represent interests in property-owning companies, funds or legally structured fractional investments. This could make it easier to divide an investment into smaller units, although property management, valuation and legal ownership would remain important.
Gold and other commodities: Tokens can represent claims linked to physical commodities held by custodians. Such products may make transfers easier, but their reliability depends on the backing arrangements, redemption rights, audits and custody safeguards.
Private credit: Investment interests in pools of loans could be represented digitally, potentially simplifying ownership records and certain administrative processes. However, the loans would remain subject to borrower defaults and the limitations of private-market liquidity.
Infrastructure: Eligible interests in energy projects, transport assets or other long-term investments could potentially be divided into digital units, subject to the applicable investment structure.
The attraction is that tokenisation could make previously cumbersome assets easier to administer and distribute.
But investors must look beyond the technology's branding. A token linked to gold is not necessarily equivalent to directly possessing physical gold, and a token linked to property does not necessarily grant direct ownership of a building.
The quality of the underlying legal claim matters more than the appearance of the token.
8. Could Financial Markets Operate 24 Hours a Day?
Traditional financial markets have opening hours, settlement schedules and operational cut-offs. Some assets can be traded internationally, but the systems supporting them do not necessarily operate continuously or synchronously.
Blockchain-based infrastructure could allow certain tokenised assets to be transferred around the clock, provided the relevant trading, custody, settlement and payment systems support continuous operation.
That could be particularly valuable for international investors operating across different time zones.
Faster settlement could also reduce the period during which one party has transferred an asset but has not yet received the corresponding payment.
In a well-designed system, delivery-versus-payment arrangements could coordinate the transfer of an asset and the associated funds, helping reduce certain settlement risks.
However, 24-hour token trading does not guarantee that every transaction can settle instantly.
The cash leg of a transaction must also be available. Banking services, liquidity, legal requirements, network congestion and operational maintenance can all create constraints.
Nor does continuous trading automatically mean better prices. Markets operating outside conventional hours may have fewer participants and thinner liquidity, potentially increasing volatility or the gap between buying and selling prices.
The opportunity is significant, but genuine round-the-clock financial markets require more than putting assets on a blockchain.
9. The Stablecoin Question: What Will Be Used to Pay?
Tokenised assets need a way to exchange value.
If an investor purchases a tokenised bond, property interest or fund unit, the transaction still requires payment. The challenge is ensuring that the asset and the money used to buy it can operate together efficiently.
Several approaches are possible, including stablecoins, tokenised commercial bank deposits and tokenised central bank money.
Stablecoins are digital tokens designed to maintain a relatively stable value against a reference asset, commonly a currency such as the US dollar. Their usefulness depends on factors including the backing arrangements, redemption mechanisms, governance and applicable regulation.
Tokenised bank deposits represent commercial bank money in digital form. Depending on their design, they may help institutions move funds within systems that support tokenised assets.
Central bank money represents a different category, carrying the monetary and institutional characteristics of claims on a central bank.
The BIS has argued that combining tokenised central bank reserves, commercial bank money and government bonds on a unified ledger could provide a foundation for a more integrated financial system. It has also warned that stablecoins do not automatically satisfy all the requirements of a sound monetary system. [3]
This debate is central to tokenisation's future.
A financial market cannot operate efficiently simply because its assets move quickly. The payment mechanism must also be reliable, legally sound and sufficiently liquid.
10. The UK Is Preparing for a Tokenised Financial System
The UK is taking practical steps to accommodate tokenisation within its existing financial framework.
In April 2026, the FCA finalised guidance on fund tokenisation and introduced an optional Direct to Fund dealing model. The framework is intended to help authorised fund managers use distributed ledger technology while operating within the UK's existing regulatory system. [6]
Fund tokenisation can involve representing an investor's units or shares in a collective investment scheme as digital tokens. Depending on the model, this could improve administrative processes, ownership records and interactions between investors and fund managers.
The FCA and Bank of England also set out a shared vision for wholesale-market tokenisation in May 2026, seeking greater clarity on areas such as prudential treatment, tokenised collateral and settlement instruments. [4]
In the United States, federal banking regulators clarified in March 2026 that eligible tokenised securities should generally receive the same capital treatment as their conventional equivalents under the applicable capital rules. They also emphasised that banks must continue to apply sound risk management and comply with relevant laws. [7]
These developments demonstrate a common regulatory principle: the technology may be new, but financial risks and legal obligations do not disappear when an asset becomes a token.
For the UK, the opportunity is to attract innovation and investment without compromising investor protection or financial stability.
11. The Risks: Fraud, Cyberattacks and Lost Access
Tokenisation could improve certain financial processes, but it introduces technical and operational challenges that cannot be ignored.
Smart-contract vulnerabilities: Software controlling token transfers or payments may contain errors that attackers can exploit. A poorly designed contract can create losses or disrupt transactions.
Custody failures: Investors may rely on a platform, custodian or wallet provider to safeguard digital assets. If that organisation is hacked, becomes insolvent or loses access to critical systems, investors may struggle to recover their holdings.
Private-key loss: In systems that rely on self-custody, losing the relevant private keys can make an asset inaccessible. Recovery mechanisms may exist in some arrangements, but they are not universal.
Fraudulent tokens: A token may claim to represent a valuable asset without providing a valid legal claim to it. Investors must verify the issuer, documentation, backing arrangements and redemption rights.
Operational failures: Blockchain networks, bridges and connected financial systems can experience outages, congestion or technical problems. A failure in one part of the system can affect transactions elsewhere.
Governance disputes: Participants may disagree about how a network should operate, who can change its rules or what happens when a transaction is disputed.
Tokenisation does not eliminate fraud or counterparty risk. It changes how those risks may appear and where responsibility lies.
Investors should be cautious of products marketed as guaranteed, risk-free or automatically secure simply because they use blockchain technology.
12. The Liquidity Illusion: Can Every Token Actually Be Sold?
One of the most persistent claims about tokenisation is that it will make illiquid assets liquid.
An asset is liquid when it can be bought or sold relatively quickly without causing a substantial change in its price.
Tokenisation can make it easier to transfer an investment interest, but it cannot guarantee that another investor will want to buy it.
Consider a token representing an interest in a commercial building. Even if the token can be transferred instantly, the underlying property may take months to sell. Its value may also depend on rental income, maintenance costs, debt and prevailing property-market conditions.
If many token holders want to sell at the same time, there may not be enough buyers.
The same problem applies to private credit, infrastructure and other investments that depend on long-term assets.
A tokenised investment may therefore offer convenient digital transfers while remaining economically illiquid.
This distinction is particularly important for retail investors, who may assume that being able to trade a token on a platform means they can always exit their position at a fair price.
The IMF's October 2026 analysis warns that tokenisation could create new financial-stability vulnerabilities alongside its potential efficiencies, including risks associated with liquidity and the speed at which problems may spread. [1]
Making an asset easier to transfer is not the same as making it safer to own.
13. Could Tokenisation Make Financial Crises Worse?
The technology could improve transparency and settlement, but it could also accelerate certain forms of financial stress.
In conventional markets, transactions may pass through multiple institutions and processes. Tokenised systems could compress some of those steps, allowing assets and payments to move more rapidly.
Under normal conditions, that could improve efficiency.
During a crisis, however, faster transactions may allow investors to sell assets, move collateral or withdraw liquidity more quickly. If large numbers of participants act at the same time, the resulting pressure could intensify market movements.
Automated systems may also react to the same signals, potentially amplifying collective behaviour if safeguards are inadequate.
Interconnected tokenised markets could create another challenge. If an asset is widely used as collateral across multiple platforms, a fall in its value may trigger additional collateral demands or forced selling elsewhere.
These risks are not unique to blockchain. Traditional financial markets already experience liquidity shocks, margin calls and contagion.
Tokenisation could nevertheless change the speed, structure and scale at which some of these mechanisms operate.
Regulators and financial institutions will need to assess how tokenised systems behave under stress, including whether they have effective circuit breakers, robust collateral arrangements and reliable ways to resolve disputes.
The objective should be to capture the benefits of faster settlement without allowing operational speed to outrun risk management.
14. Who Wins—and Who Could Lose?
The effects of tokenisation will vary across the financial industry.
Banks could benefit from more efficient payments, collateral management and financial-market operations. However, they may also face competition from new infrastructure providers and alternative settlement models.
Asset managers could reduce some administrative costs and develop new ways to distribute investment products. They would still need to manage investment risk, legal obligations and investor servicing.
Exchanges and intermediaries may see some activities automated or reorganised. Their future role could depend increasingly on providing trusted infrastructure, liquidity, compliance and investor protection.
Technology companies could gain opportunities to build wallets, custody systems, compliance software and blockchain infrastructure. Competition may be intense, and the sector's success will depend on adoption rather than technological claims alone.
Investors could gain access to new investment structures and potentially benefit from lower costs. But they may also encounter unfamiliar products, new custody risks and limited secondary-market liquidity.
Governments and regulators could benefit from more efficient financial infrastructure while facing new challenges around supervision, cross-border rules and the management of systemic risk.
Tokenisation is unlikely to eliminate every existing financial intermediary. Instead, it may change which services are valuable and how they are delivered.
The institutions that adapt successfully could benefit. Those that rely heavily on inefficient processes may face greater competitive pressure.
15. Three Possible Futures for the Tokenised Economy
The long-term outcome remains uncertain, but three scenarios illustrate the range of possibilities.
Scenario one: Gradual integration. Tokenisation becomes established in selected areas, including government bonds, investment funds and collateral management. Traditional institutions adopt the technology where it offers measurable benefits, while most financial activity continues to use existing infrastructure.
Scenario two: A major financial transformation. Interoperable tokenised systems become widely adopted, allowing assets and payments to move more efficiently across markets. Administrative costs fall, investment distribution changes and certain transactions become faster and easier to automate.
Scenario three: Fragmentation and setbacks. Different platforms develop incompatible systems, legal uncertainty limits adoption and high-profile failures damage confidence. Tokenisation remains useful in specialist markets but falls short of transforming global finance.
The most plausible path may combine elements of the first two scenarios, with uneven adoption across asset classes and jurisdictions.
The IMF's October 2026 analysis highlights this tension: tokenisation could eventually reshape financial markets, but the present market remains fragmented and its wider benefits depend on overcoming important infrastructure, regulatory and risk-management challenges. [1]
Success will depend less on how many assets are described as tokenised and more on whether the technology produces reliable improvements for investors, businesses and financial institutions.
16. The Verdict: Evolution, Not an Overnight Revolution
Tokenisation could become one of the most important developments in financial infrastructure over the coming decade.
By representing assets on programmable digital ledgers, it offers the possibility of more efficient settlement, streamlined administration, fractional investment structures and improved coordination between financial institutions.
The technology is already attracting attention from regulators, banks and asset managers. The UK's evolving framework and the BIS's work on a unified ledger demonstrate that tokenisation is being considered as part of the future of mainstream finance.
However, several barriers remain. Markets are fragmented, legal rights depend on the structure of each product, liquidity cannot be guaranteed and technical vulnerabilities introduce risks that investors must understand.
Tokenisation also cannot remove the fundamental realities of finance. Borrowers can still default, assets can still lose value, investors can still be defrauded and markets can still experience crises.
The most important question is not whether blockchain will replace every bank, exchange or broker. It is whether tokenisation can make the financial system meaningfully more efficient, accessible and resilient.
If it succeeds, people may eventually interact with tokenised investments without even thinking about the underlying technology. Buying a fund, transferring a bond or settling a transaction could become faster and more seamless.
But the future will not be determined by technology alone. Legal certainty, investor confidence, interoperability and sound regulation will decide whether tokenisation becomes a genuine financial revolution or remains a collection of promising but fragmented experiments.
The tokenised economy is taking shape. Its ultimate impact will depend on whether the industry can turn the promise of digital ownership into a system people can actually trust.
Sources
[1] International Monetary Fund — What Is Needed for Tokenization to Deliver, 8 October 2026 https://www.imf.org/en/blogs/articles/2026/10/08/blog-what-is-needed-for-tokenization-to-deliver
[2] US Securities and Exchange Commission — Statement on Tokenized Securities, 28 January 2026 https://www.sec.gov/newsroom/speeches-statements/corp-fin-statement-tokenized-securities-012826-statement-tokenized-securities
[3] Bank for International Settlements — Next-generation Monetary and Financial System Takes Shape, Based on a Tokenised Unified Ledger, 24 June 2025 https://www.bis.org/media-releases/20250624-next-generation-monetary-and-financial-system-takes-shape-based-tokenised-unified-ledger-bis.htm
[4] Financial Conduct Authority and Bank of England — FCA and Bank of England Set Out Shared Vision for Tokenisation in UK Wholesale Markets, 18 May 2026 https://www.fca.org.uk/news/press-releases/fca-and-bank-england-set-out-shared-vision-tokenisation-uk-wholesale-markets
[5] CoinGecko Research — RWA Report 2026, updated 13 May 2026 https://www.coingecko.com/research/publications/rwa-report-2026
[6] Financial Conduct Authority — FCA Sets Out Guidance to Support Innovation in Fund Tokenisation, 30 April 2026 https://www.fca.org.uk/news/press-releases/fca-sets-out-guidance-support-innovation-fund-tokenisation
[7] Federal Reserve Board — Agencies Clarify the Capital Treatment of Tokenized Securities, 5 March 2026 https://www.federalreserve.gov/newsevents/pressreleases/bcreg20260305a.htm
Published by Banx Network. This article is part of the Banx decentralized media programme, powered by the BXE token on the XRP Ledger.